Just the Tip:
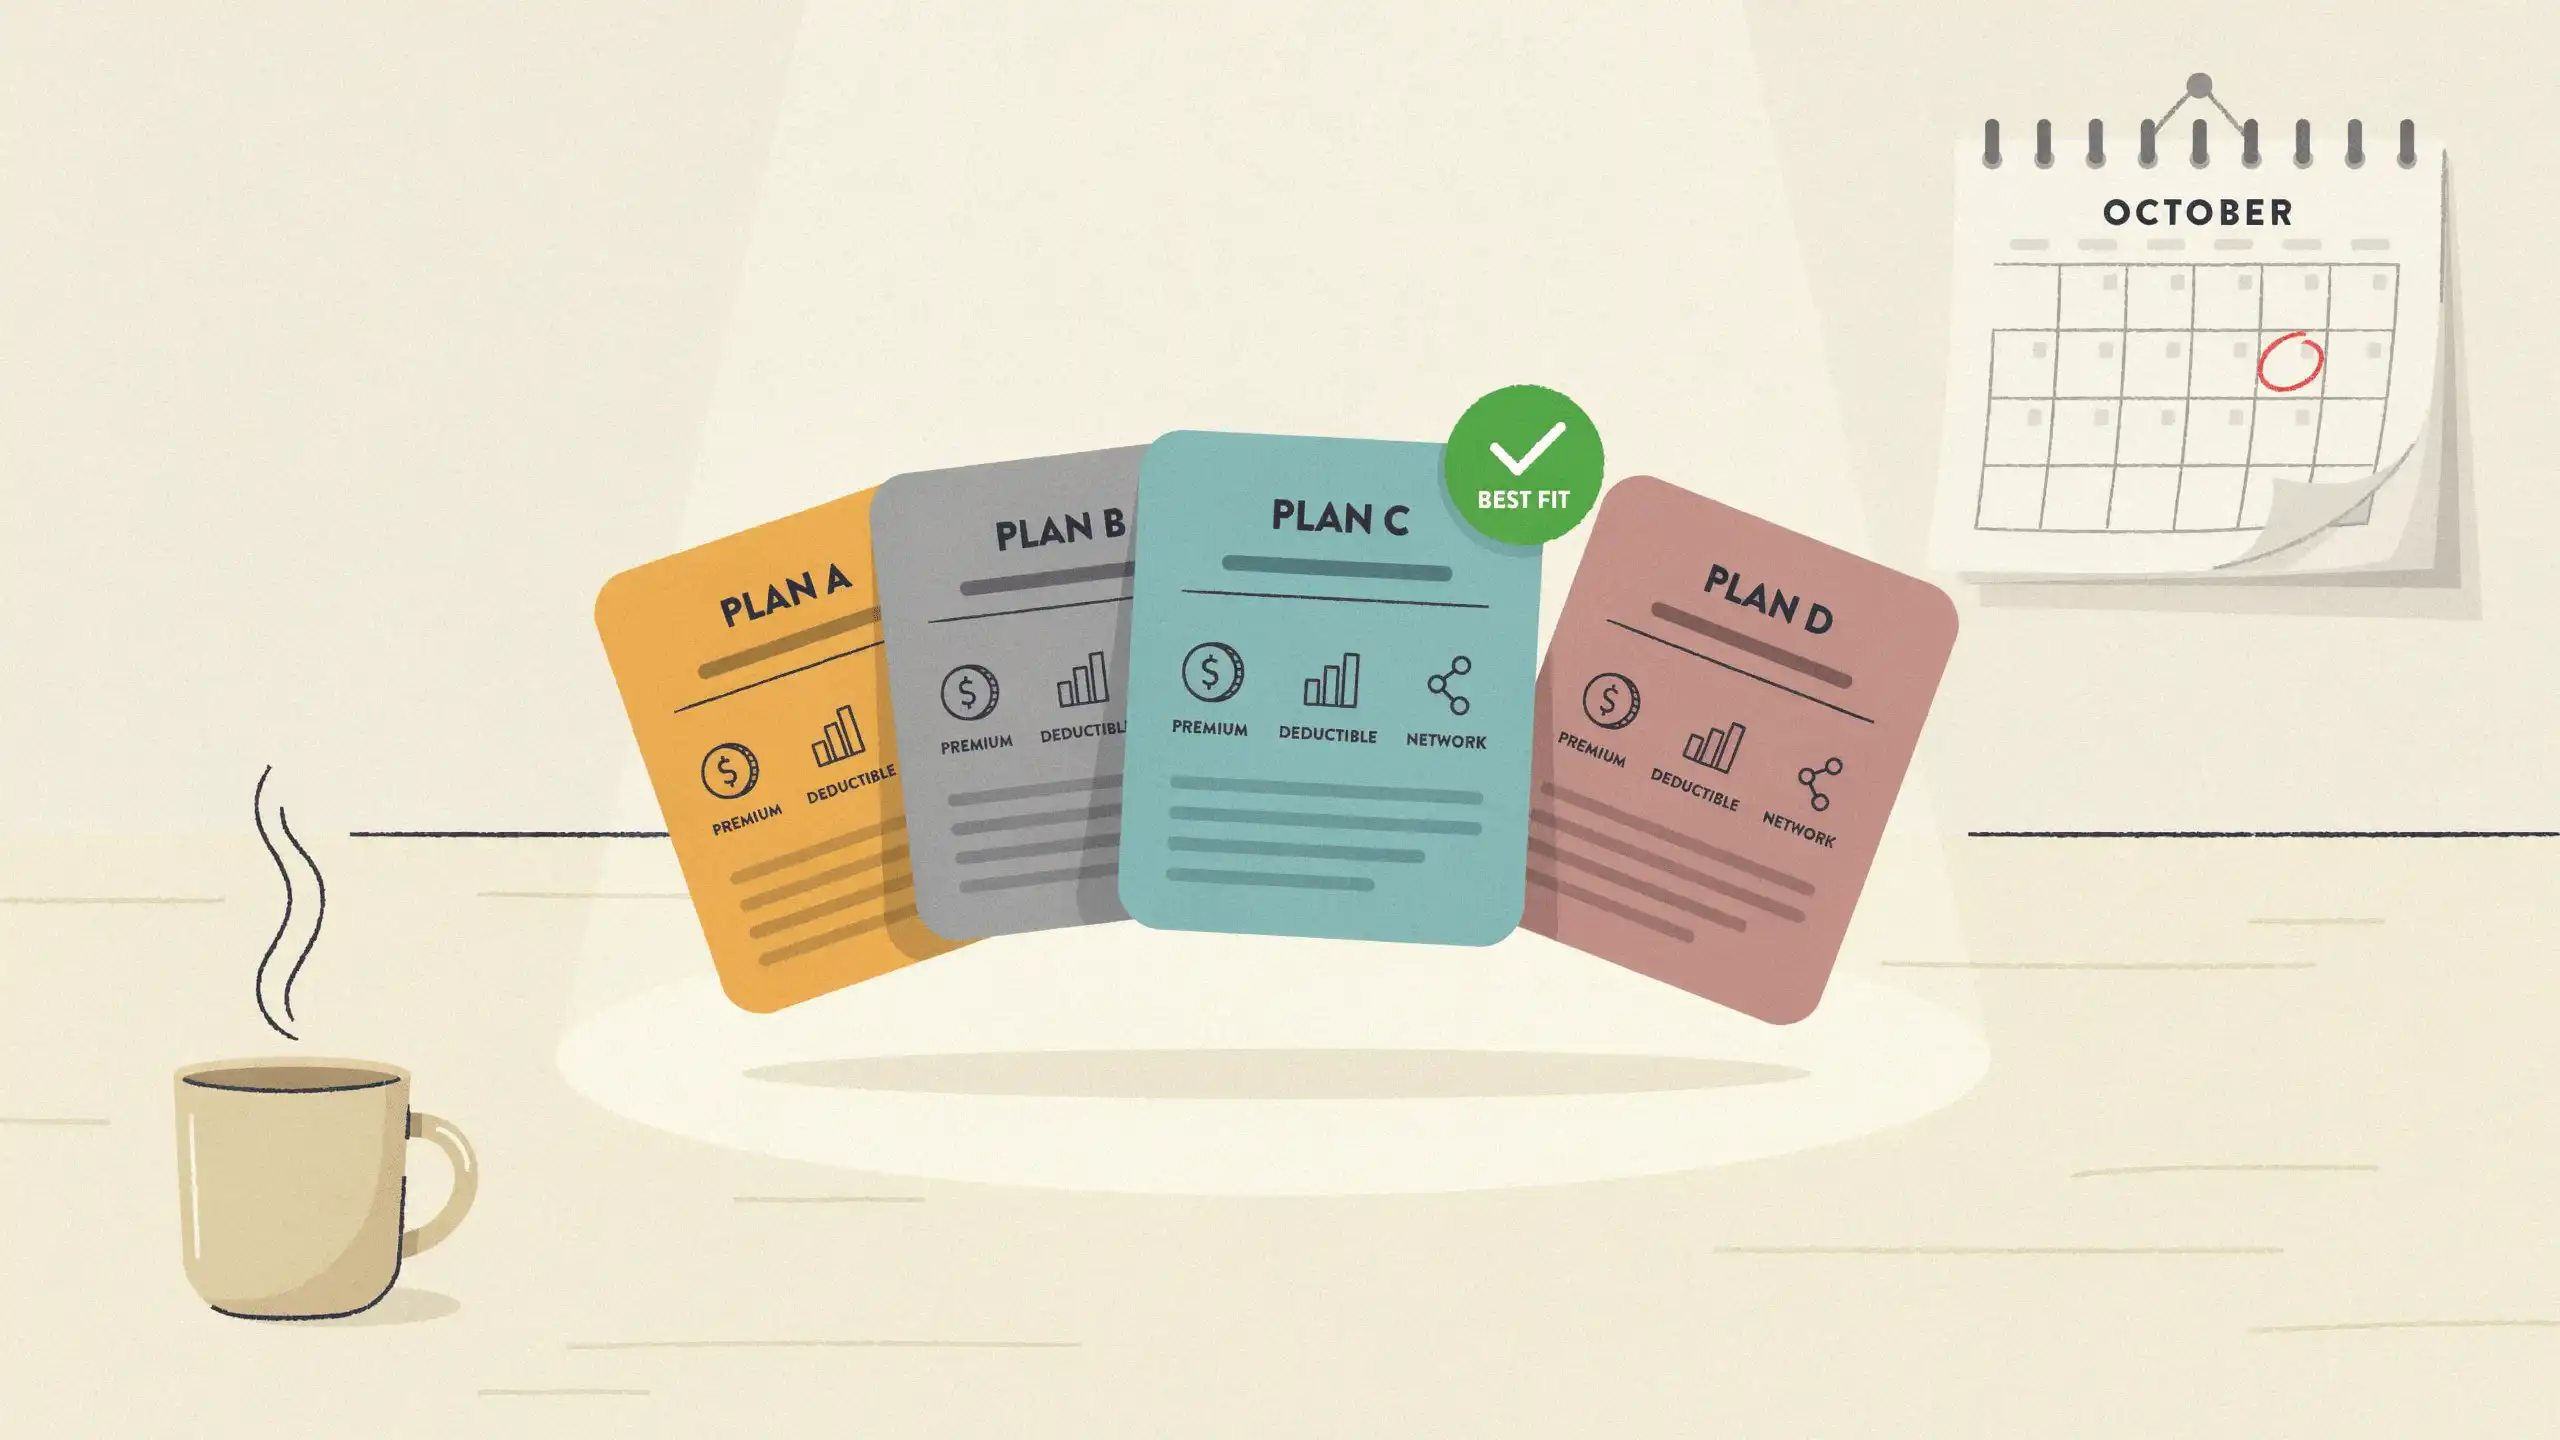
Letting your health plan roll over at open enrollment means buying next year’s coverage without checking next year’s prices. Before the window closes, add 12 months of each option’s premiums to what you’d expect to pay out of pocket, and compare the totals. Then confirm your doctors and prescriptions are still covered.
In a 2024 Voya Financial survey, 91% of workers with employer benefits said they usually stick with last year’s health plan, and 49% give their benefits less than 20 minutes during open enrollment.
Staying put assumes nothing changed. A renewal can bring a new premium, deductible, provider network, and drug list, and your own needs can shift with a new baby, a new prescription, or a surgery you’ve been putting off.
The cheapest plan is the one with the lowest total for the year you’re about to have, and the premium is only part of that total. Say one plan costs you $200 a month and caps your share of covered care at $4,000 a year, its out-of-pocket maximum. Another costs $80 a month with a $7,000 cap. If you barely use care, the $80 plan saves you $1,440. In a year bad enough to hit both caps, it costs you $1,560 more.
Run the numbers before your enrollment window closes. After that, you’re locked in until next year unless an event like a marriage, birth, or adoption gives you at least 30 days to make changes.
- Get the Summary of Benefits and Coverage for every plan. It lays out deductibles, copays, and out-of-pocket maximums in one standard format, and you’re entitled to one within seven business days of asking.
- Pull last year’s claims from your insurer’s website to see what care you used, then add anything you know is coming.
- Price that care under each plan’s deductible and copays, and add 12 months of premiums. Then price a bad year by adding each plan’s out-of-pocket maximum to its premiums. Subtract any money your employer puts into a health savings account for that plan.
- Look up your doctors in next year’s network and your prescriptions on next year’s drug list, along with what each drug will cost you.
If one plan comes out cheaper both times, take it. If they split, choose the one that wins your expected year, as long as you could pay its out-of-pocket maximum from savings.
Make & Save More Money, Spend Less Time
One money tip, every morning
Join 50,000+ readers. Actionable, free, no nonsense – just the tip.
No spam, ever. Unsubscribe anytime.
Editorial & Advertiser Disclosure: The editorial content on this page is not provided, commissioned, reviewed, approved, or otherwise endorsed by any advertiser. Opinions expressed here are ours alone, not those of any advertiser. The offers that appear on this site are from companies that compensate us. That compensation may influence which products we cover and where and how they appear on a page – including the order in which they appear – but it does not influence our evaluations, ratings, or opinions. We do not include every company or offer available in the marketplace.
Related:
Publisher: Source link